5 Medicare Mistakes to Avoid During Annual Enrollment
5 Medicare Mistakes to Avoid During Annual Enrollment
Medicare Annual Enrollment is here.
And every year, we see the same thing happen.
The commercials start.
The mail piles up.
Everyone suddenly seems to have an opinion about which Medicare plan you should choose.
Your neighbor loves their plan.
Your friend tells you theirs is better.
A commercial is promising benefits that sound amazing.
And somewhere in the middle of all that noise, you're supposed to figure out what's actually right for you.
Medicare's Annual Enrollment Period runs from October 15 through December 7. During this time, people with Medicare can review their health and drug coverage and make certain changes for the following year.
Medicare specifically recommends reviewing coverage annually because plan costs, benefits, and providers can change...and so can your healthcare needs.
At C & K Healthcare Advisors, we don't believe everyone needs to change plans during AEP.
But we do believe everyone should understand what they're keeping before deciding to keep it.
Here are five mistakes we hope you'll avoid this Annual Enrollment Period.
Mistake #1:
Automatically Keeping Your Plan Without Reviewing It
You've had the same Medicare plan all year.
You like it.
It worked.
So why bother looking at it again?
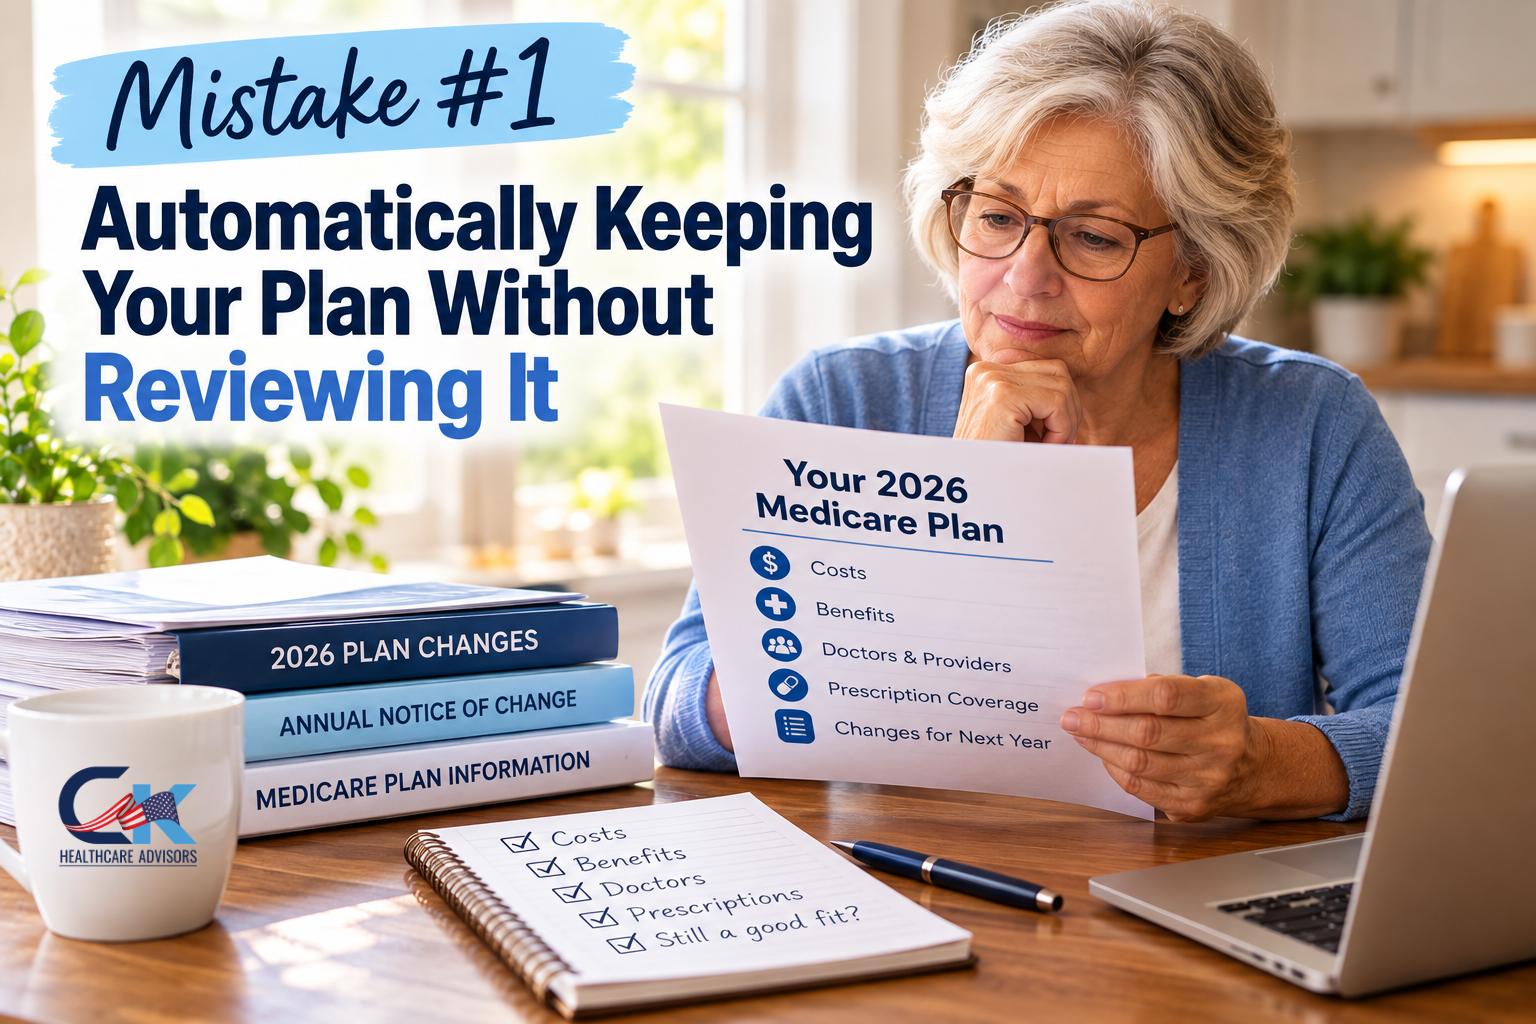
Because next year's version of your plan may not be identical to this year's.
Costs, benefits, provider participation and other plan details can change from year to year. Your plan sends information explaining upcoming changes, and Medicare recommends reviewing those notices before deciding whether your existing coverage still meets your needs.
But your plan isn't the only thing that might have changed.
Maybe you:
Started a new medication.
Received a new diagnosis.
Started seeing another specialist.
Had surgery.
Moved.
Started traveling more.
Or simply used healthcare differently this year.
You don't need to change plans simply for the sake of changing.
In fact, after reviewing everything, you may discover:
"My current coverage still works really well for me."
Great!
Then you've made an informed decision to stay rather than accidentally allowing your coverage to renew without knowing what's changing.
The mistake isn't keeping your plan.
The mistake is keeping it without reviewing it first.
Mistake #2:
Choosing a Plan Based Only on the Monthly Premium
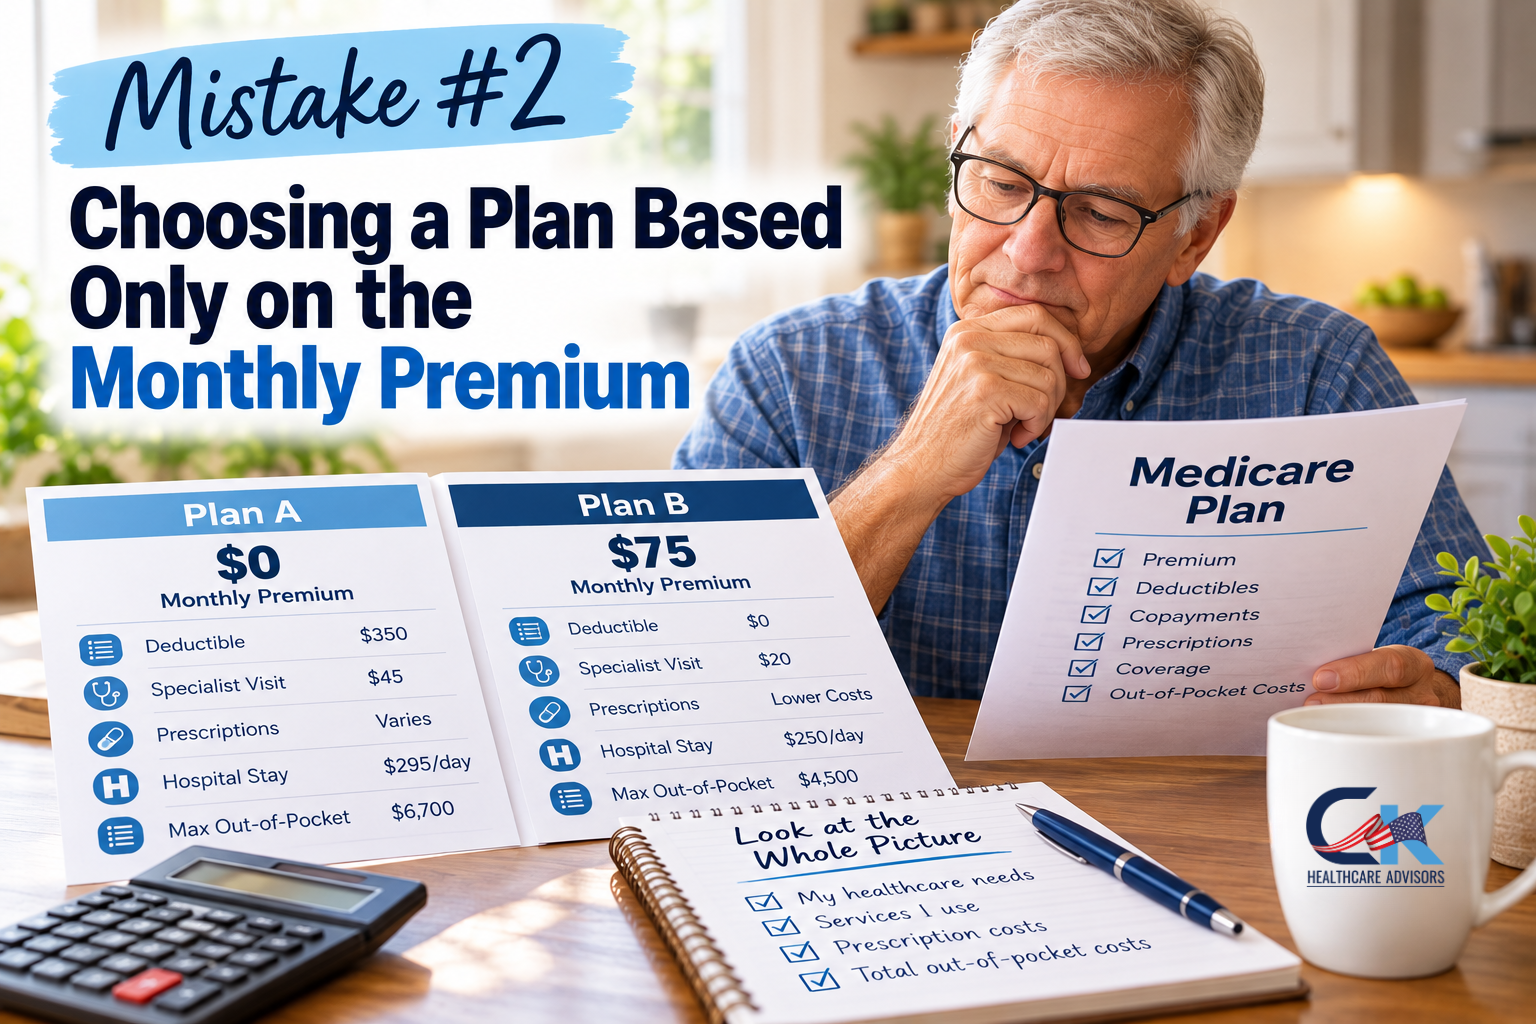
We understand why that big $0 PREMIUM gets people's attention.
But please don't stop there.
A Medicare Advantage plan can have a $0 additional plan premium while still having other costs when you receive healthcare.
You also generally continue paying your Medicare Part B premium.
Depending on the plan, there may be deductibles, copayments, coinsurance and other out-of-pocket expenses.
Medicare Advantage plans also have an annual limit on what you pay for covered Medicare services.
So instead of asking only:
"What's my monthly premium?"
Ask:
"What could my healthcare realistically cost me throughout the year?"
Look at the services you actually use.
How much is a specialist visit?
What could you pay for outpatient procedures?
What about diagnostic testing?
Hospitalization?
Physical therapy?
Prescription drugs?
And what is the plan's maximum out-of-pocket limit for covered medical services?
A lower premium doesn't automatically mean lower total healthcare costs.
The goal isn't simply finding the lowest number on the first page.
It's understanding the whole picture.
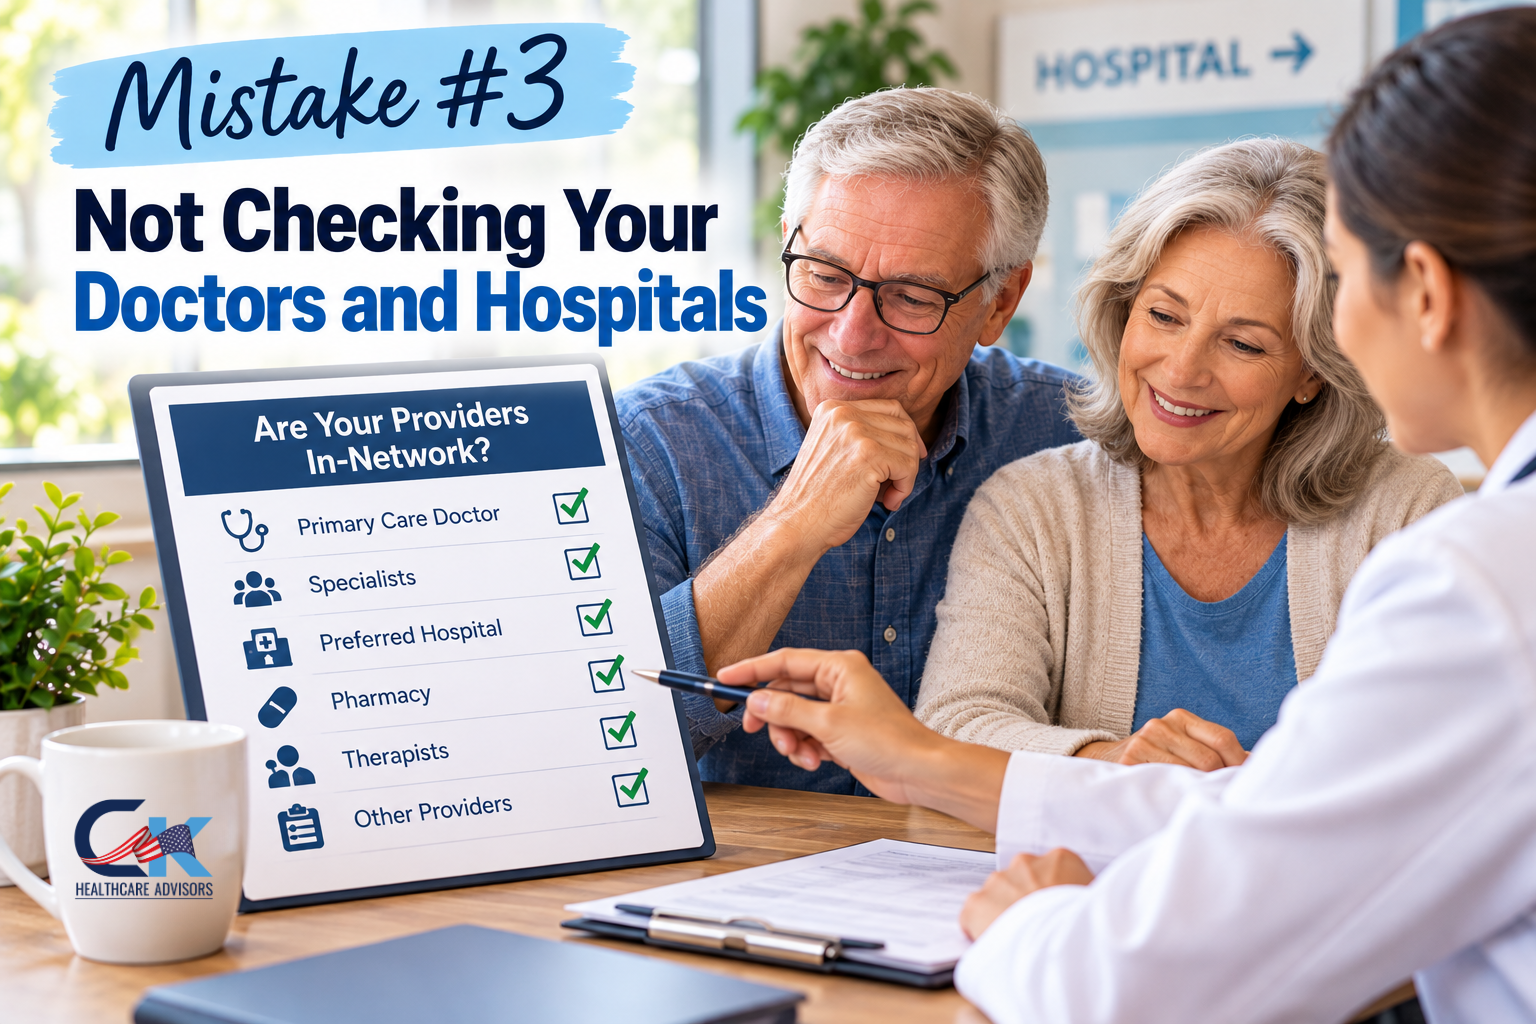
Mistake #3:
Not Checking Your Doctors and Hospitals
This one can create a very unpleasant surprise.
You find a Medicare Advantage plan that sounds wonderful.
The benefits look good.
The costs seem reasonable.
You enroll.
Then you discover your favorite doctor isn't in the plan's network.
Depending on the type of Medicare Advantage plan, you may need to use providers within the plan's network and service area for non-emergency care, or you may pay more for out-of-network care.
That's why your Medicare review should include more than your primary care doctor.
Think about everyone involved in your care:
Primary care physician
Cardiologist
Oncologist
Orthopedic specialist
Dermatologist
Therapists
Preferred hospital
Pharmacy
Other specialists you regularly see
If there's a provider you absolutely don't want to lose, tell your advisor.
And because provider participation can change, it's wise to verify network status rather than relying solely on what was true last year.
Your relationship with your healthcare providers matters.
Your Medicare coverage should take that into consideration.
Mistake #4:
Forgetting About Your Prescriptions
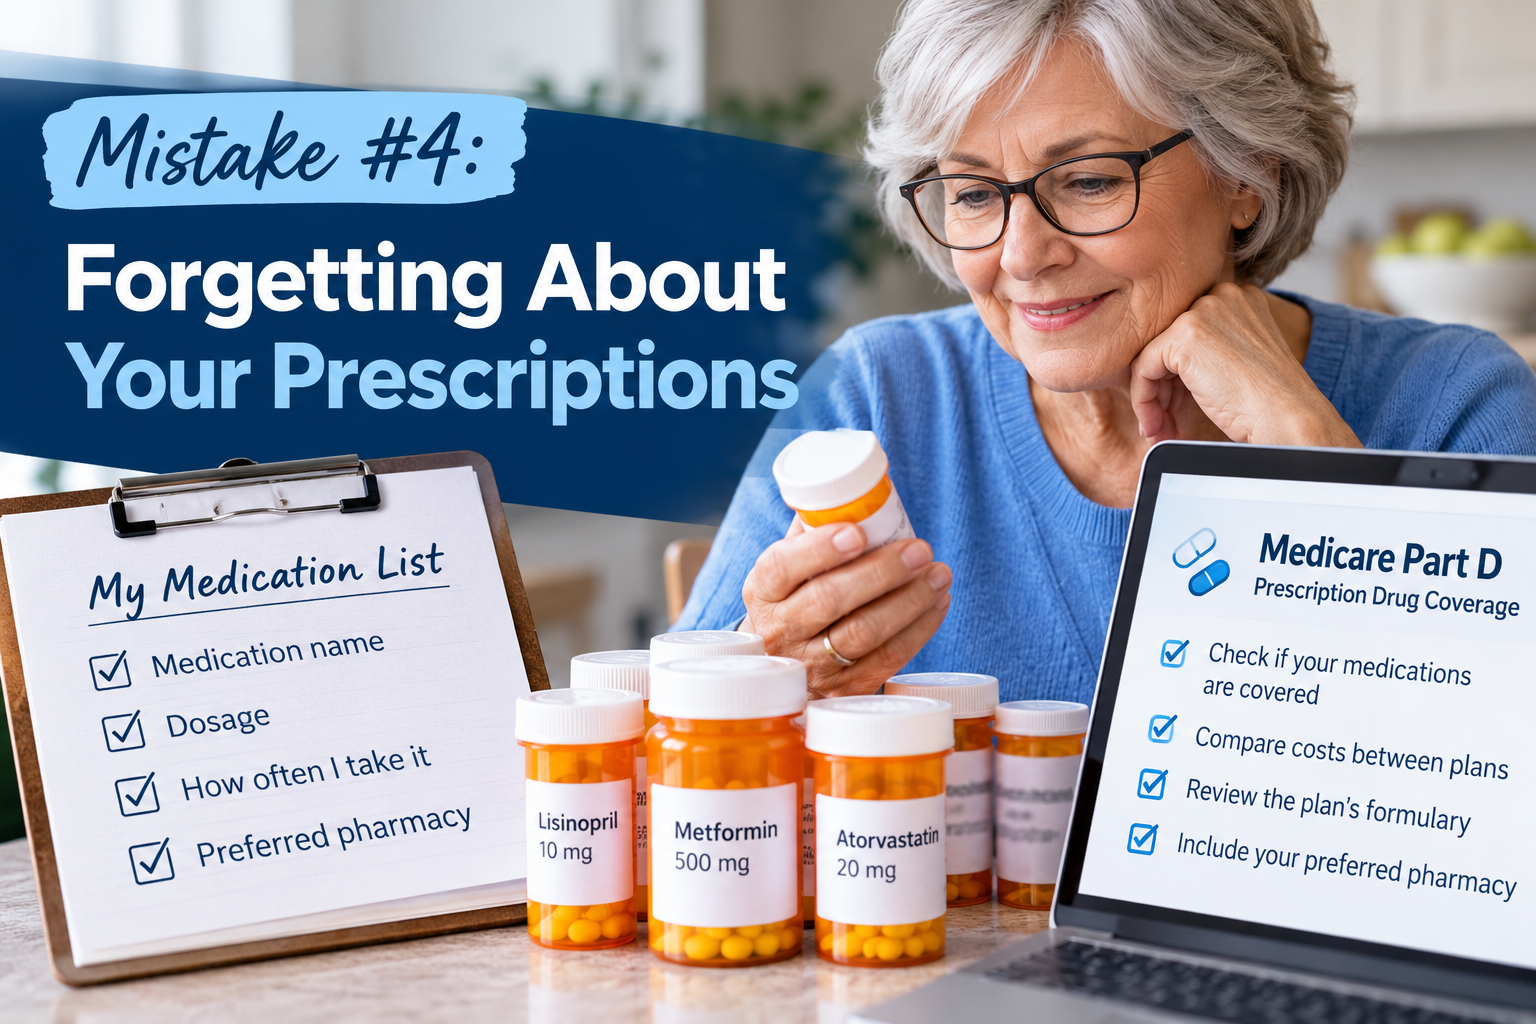
Please bring your medication list to your Medicare review.
All of it.
Not:
"I take a little white pill for blood pressure..."
We love you, but we're going to need more information than that. 😄
Write down the exact medication name, dosage, how often you take it, and your preferred pharmacy.
Medicare drug plans have formularies (lists of medications they cover) and coverage and costs can vary between plans.
Medicare's plan comparison tools allow beneficiaries to enter their prescriptions and preferred pharmacies to estimate costs under different options.
This matters because two plans with similar premiums could produce very different prescription costs for the same person.
A plan can look wonderful until you discover that an important medication isn't covered the way you expected.
Your prescriptions aren't a small detail in the Medicare conversation.
They're one of the first things we want to know about.
Mistake #5:
Choosing a Medicare Plan Because Your Friend Loves It
We hear this one all the time.
"My neighbor has this plan and she LOVES it."
We're glad she does!
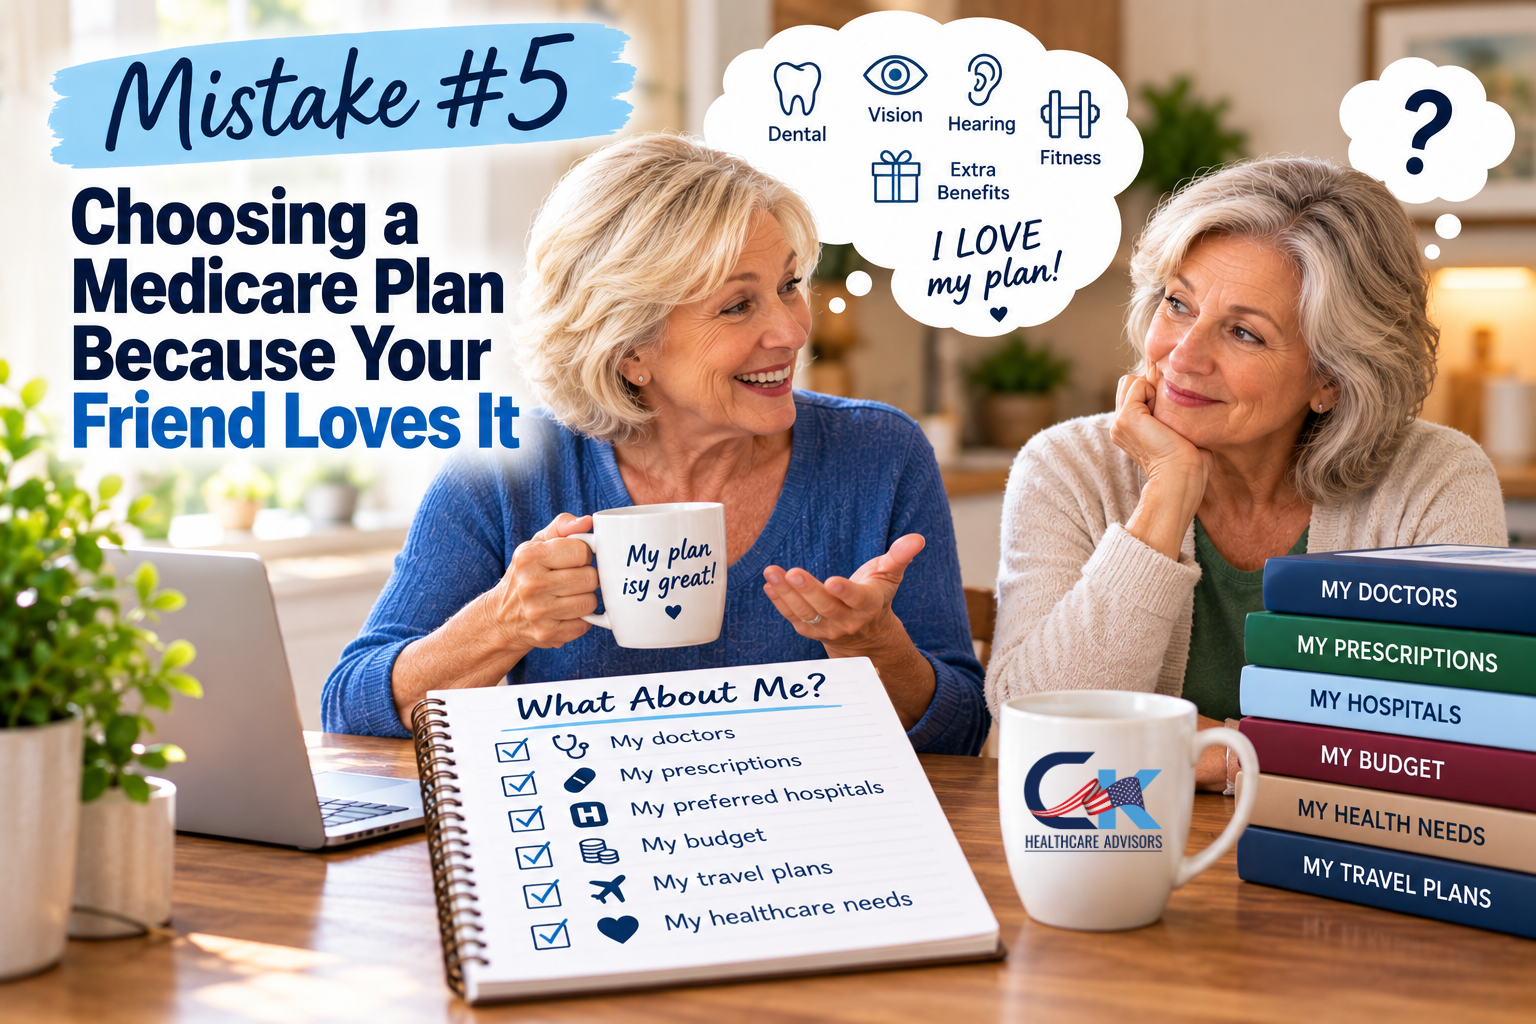
But your neighbor doesn't necessarily have:
Your doctors.
Your prescriptions.
Your health conditions.
Your hospital preferences.
Your budget.
Your travel habits.
Or your healthcare priorities.
Medicare itself recommends comparing plans based on factors including costs, prescription coverage, providers and pharmacies.
The plan that's a fantastic fit for your best friend could be completely wrong for you.
And the opposite is true too.
There is no Medicare plan that is automatically perfect for everyone.
That's why we don't start a Medicare conversation by asking what plan your neighbor has.
We start by asking about you.
Bonus Mistake:
Choosing Based on One Exciting Extra Benefit
We have to sneak in a sixth one.
Dental!
Vision!
Hearing!
Fitness!
And other supplemental benefits can absolutely be worth considering when they're offered by a particular Medicare Advantage plan.
But don't let one attractive benefit distract you from everything else.
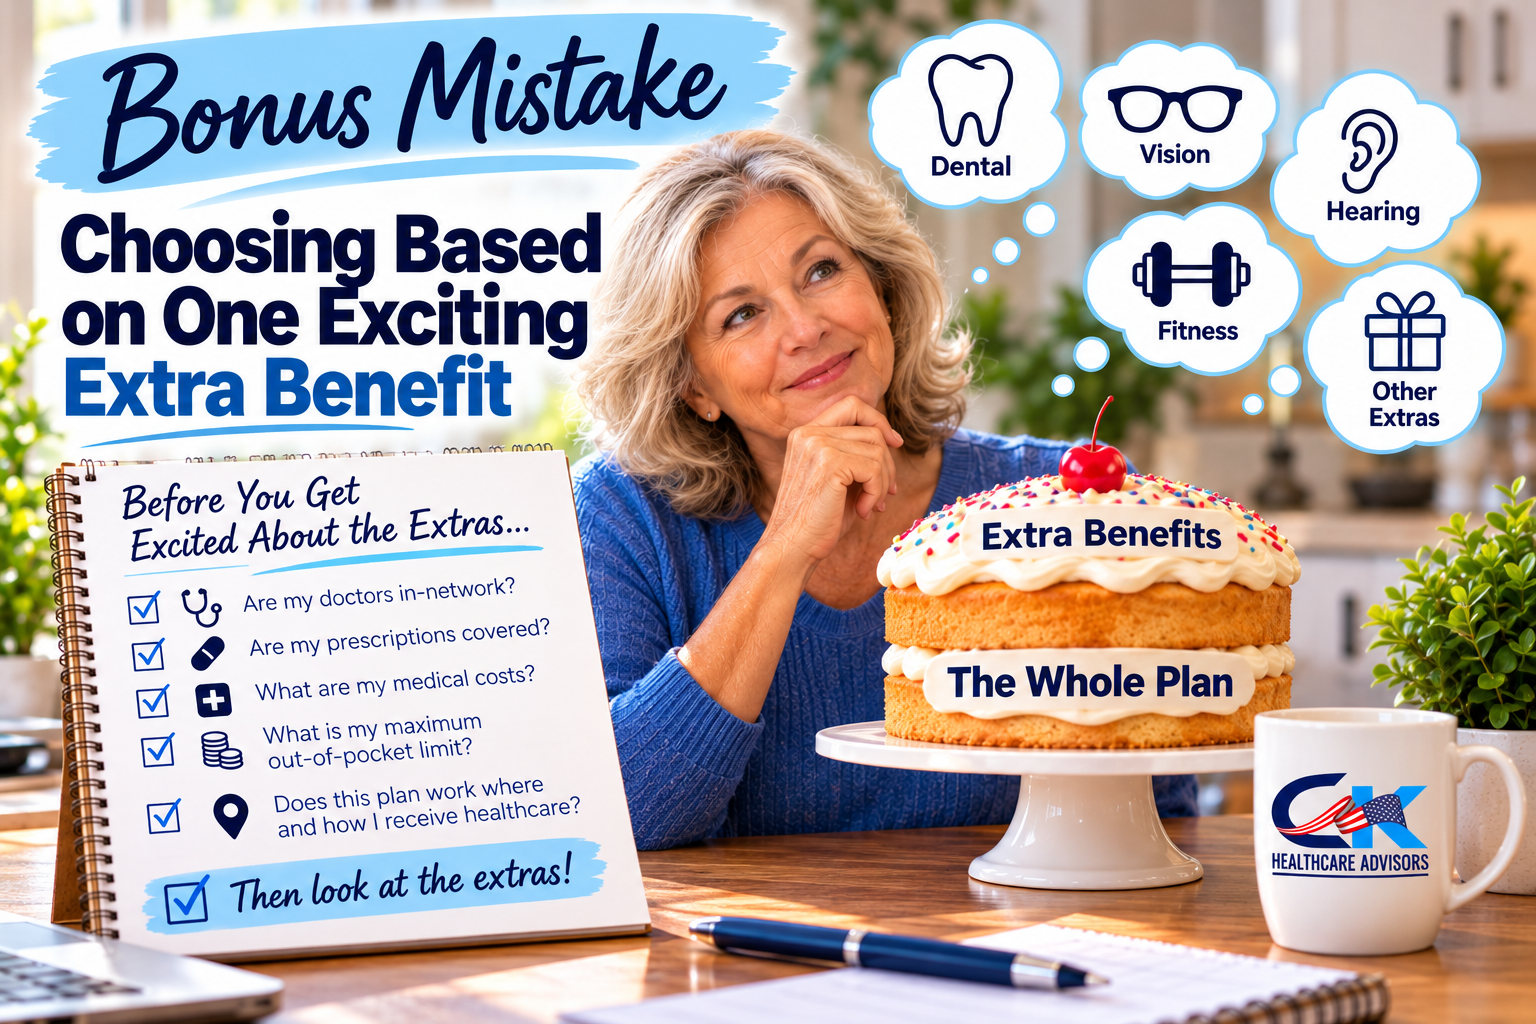
Before you get excited about an extra, make sure you've already asked:
Are my doctors in-network?
Are my prescriptions covered?
What are my medical costs?
What is my maximum out-of-pocket exposure?
Does this plan work where and how I receive healthcare?
Then look at the extras.
The icing is great....but make sure you like the cake.
A Personal Thought
If I were helping someone in my own family choose Medicare coverage,
I wouldn't start by asking:
"Which plan has the coolest benefits?"
I'd sit down at the table with them.
We'd have their medication bottles nearby.
We'd write down their doctors.
We'd talk about their health.
I'd want to know if they're planning to travel.
I'd want to know what they're worried about.
And I'd probably ask them ten times:
"Okay, but is there anything else you take?" 😂
Because that's what this decision deserves.
Medicare coverage affects something incredibly personal.
Your healthcare.
You deserve more than a quick recommendation based on a premium, commercial, postcard, or what worked for somebody else.
You deserve someone willing to listen first.
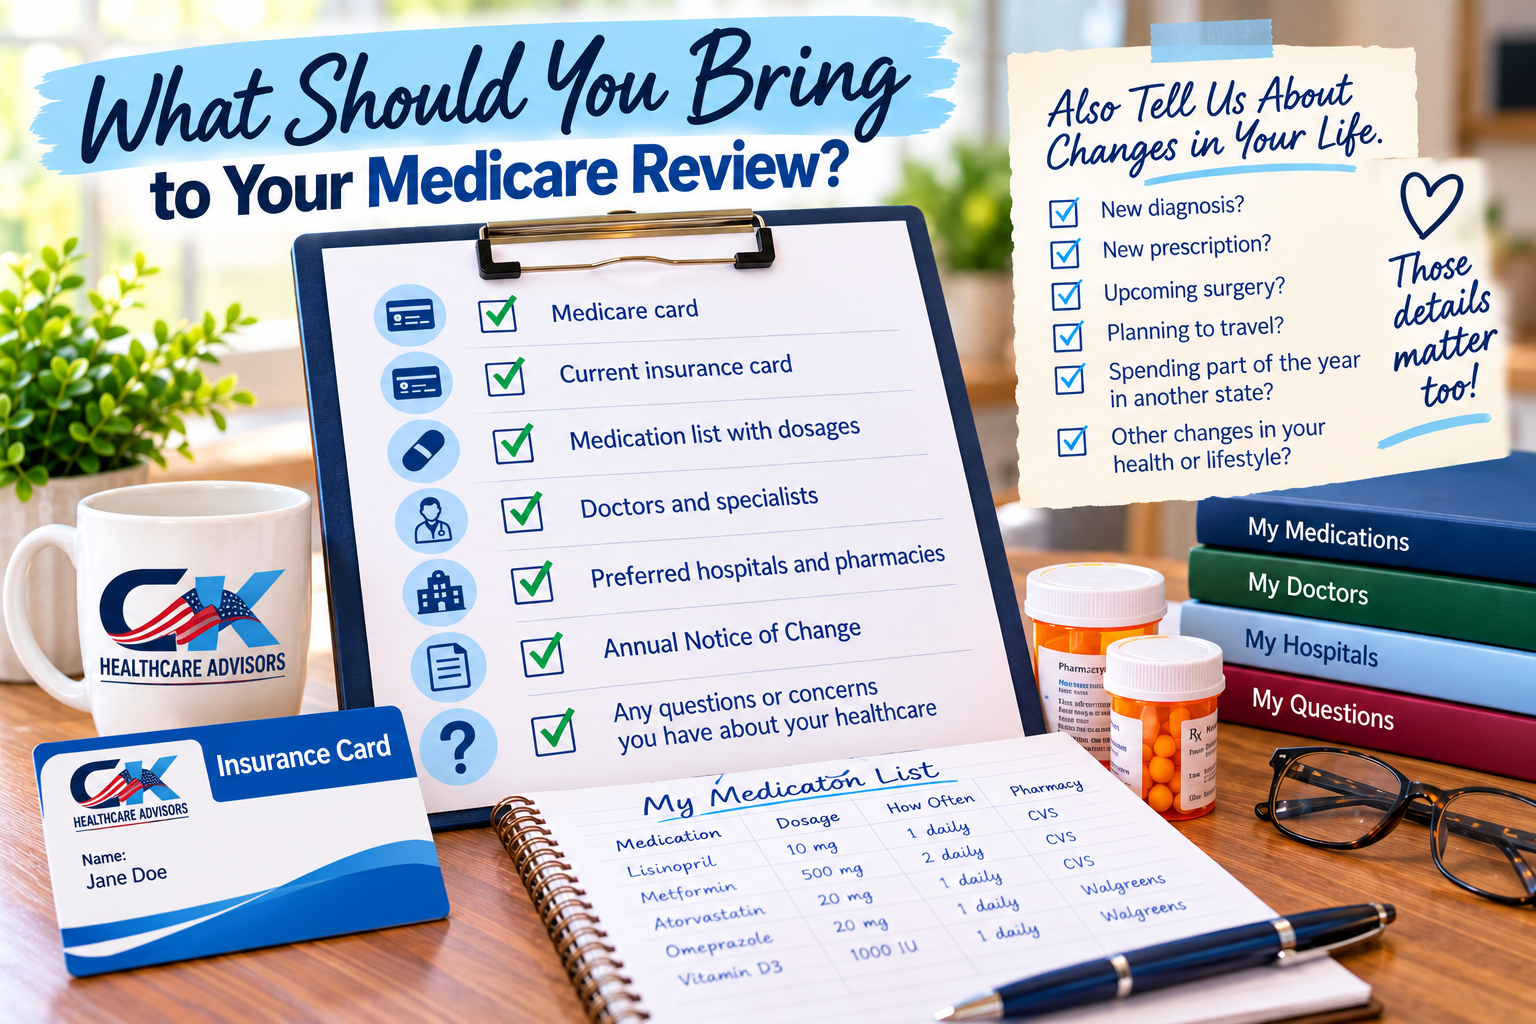
What Should You Bring to Your Medicare Review?
Before your appointment, gather your
Medicare card
Current insurance card
Medication list with dosages
Doctors and specialists
Preferred hospitals and pharmacies
Annual Notice of Change
And any questions or concerns you have about your healthcare.
Also tell us about changes in your life.
New diagnosis?
New prescription?
Upcoming surgery?
Planning to travel?
Spending part of the year in another state?
Those details matter too.
Let's Make Your Medicare Decision About YOU
At C & K Healthcare Advisors, Annual Enrollment isn't about seeing how many people we can move from one plan to another.
Sometimes, after reviewing everything, the answer may be:
"You know what? Your current coverage still fits you well."
Other times, we may find something worth taking a closer look at.
Either way, our goal is the same:
We want you to understand your options and feel confident about your decision.
Medicare Annual Enrollment runs October 15 through December 7,
and changes made during this period generally take effect January 1.
Before You Choose Your 2027 Medicare Coverage,
Let's Review It Together.
Bring us your doctors.
Bring us your medications.
Bring us your questions.
And yes. You can even tell us which plan your neighbor loves. 😉
We'll listen, explain your options in everyday language, and help you look at the things that actually matter for your health, your budget, and your life.
Because at C & K Healthcare Advisors,
you're not just another Medicare policy.
🩵We treat you like family🩵