You Saved for Retirement. Now How Do You Turn Those Savings Into Income?
You Saved for Retirement
Now How Do You Turn Those Savings Into Income?
For most of your working life, retirement planning probably centered around one goal:
Save.
Save through your 401(k).
Build your IRA.
Put money away.
Invest.
Prepare for the future.
Then retirement arrives, and suddenly the question changes.
Instead of asking, "How much can I save?" you start asking:
"How do I make what I've saved last?"
That's a very different feeling.
For decades, a paycheck arrived on a regular schedule. Retirement can mean creating your own "paycheck" from Social Security, pensions, savings, investments, annuities, and other income sources.
At C & K Healthcare Advisors, we believe retirement income planning isn't simply about accumulating the largest account balance possible.
It's about creating a plan that helps you feel comfortable actually living the retirement you worked so hard to reach.
Retirement Changes the Financial Conversation
While you're working, a bad month in the market may be frustrating, but you may still have years of employment ahead of you.
Once you're retired and regularly withdrawing money, those ups and downs can feel very different.
Now you may be thinking about:
Monthly living expenses
Healthcare costs
Inflation
Market fluctuations
Unexpected expenses
How long your savings need to last
What you'd like to leave behind
And perhaps the biggest question:
"What if I live longer than I planned for?"
Living a long, healthy life is something to celebrate. Financially, however, longevity needs to be part of your retirement strategy.
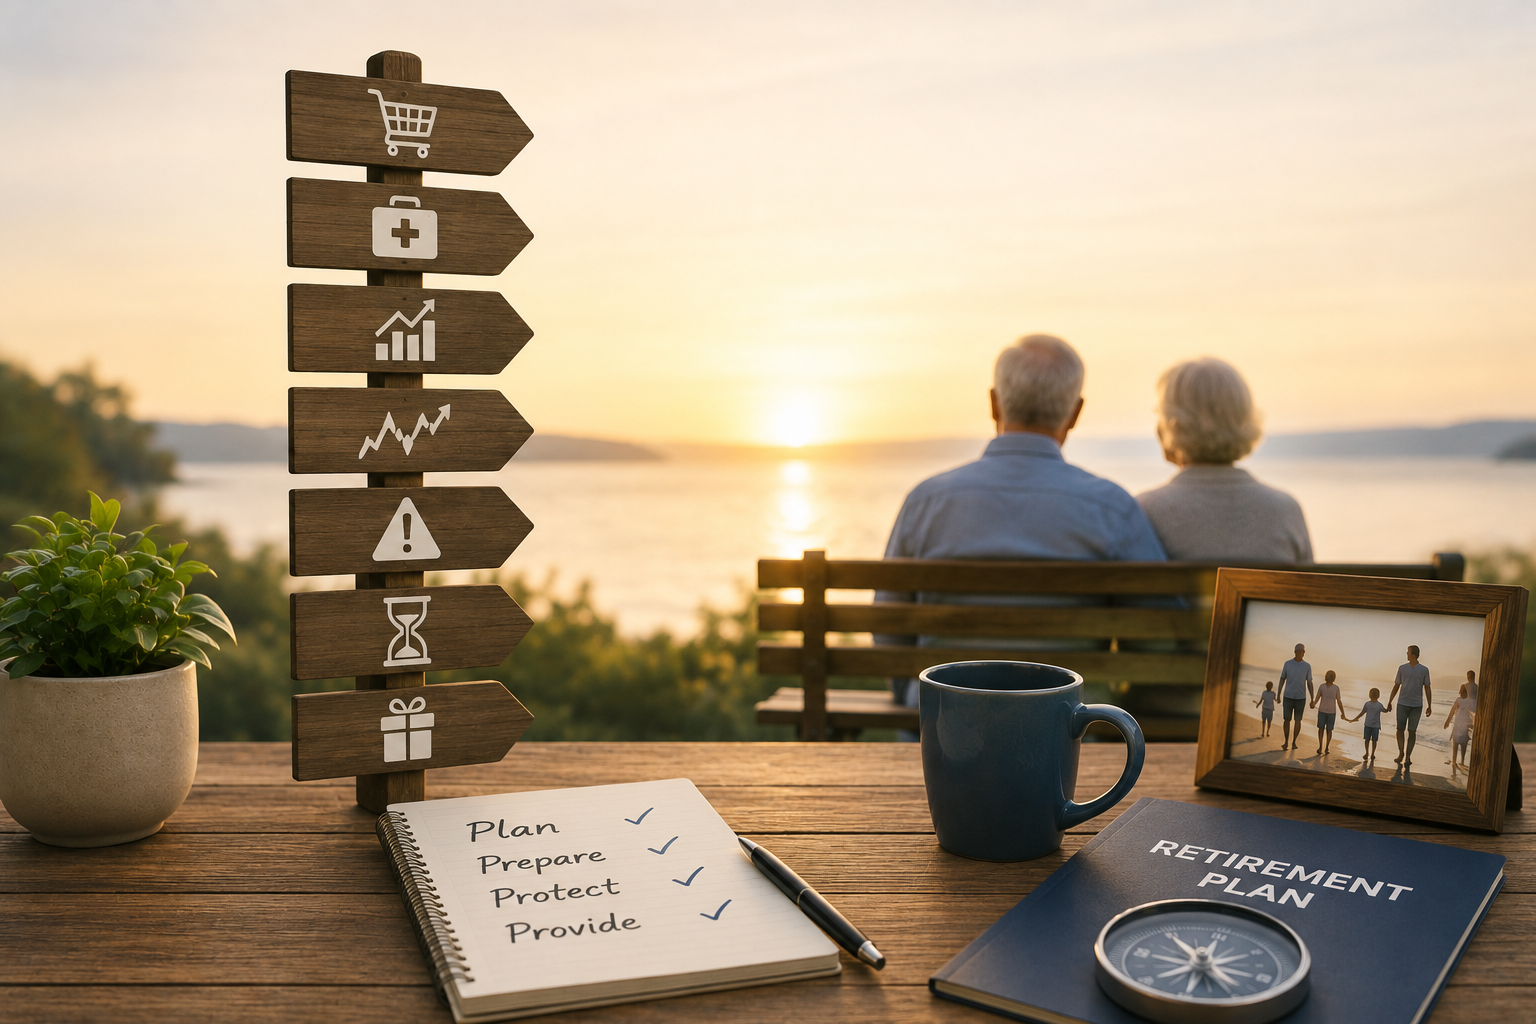
Start With Your Retirement "Paycheck"
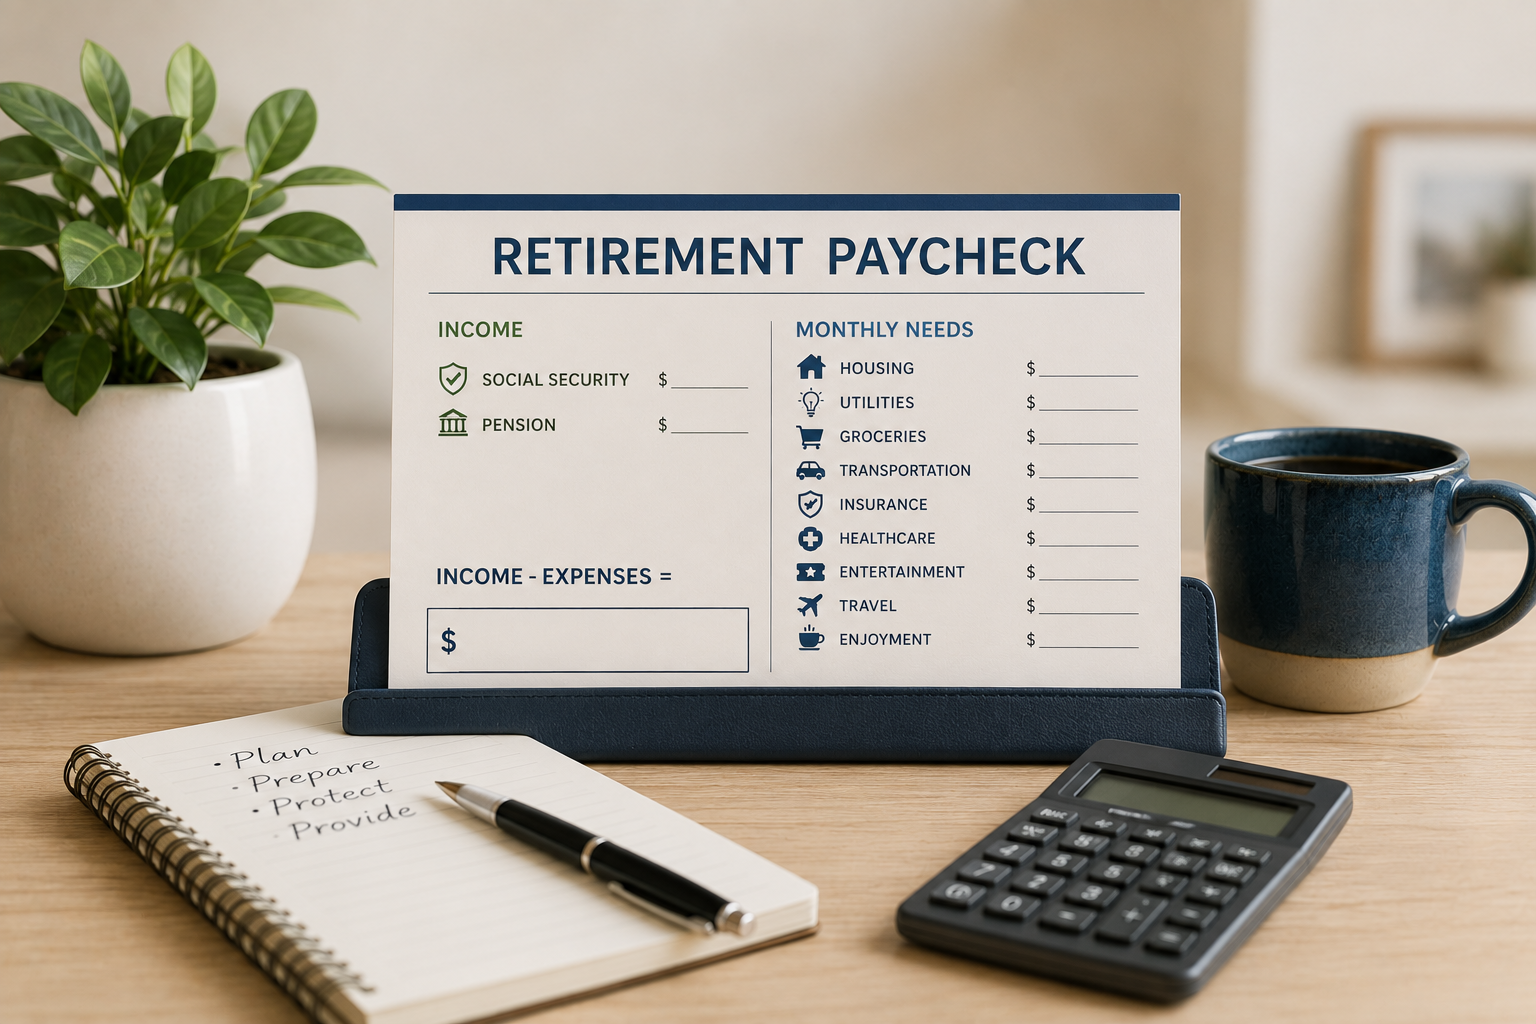
Before talking about products, it helps to understand how much income you'll actually need.
Think about the expenses that will continue every month:
Housing.
Utilities.
Groceries.
Transportation.
Insurance.
Healthcare.
Entertainment.
Travel.
And, of course, a little room for enjoying yourself.
Then look at the dependable income you already expect to receive, such as Social Security or a pension.
If your regular expenses are greater than your predictable income, you'll need a strategy for filling that gap.
That's where retirement income planning becomes especially important.
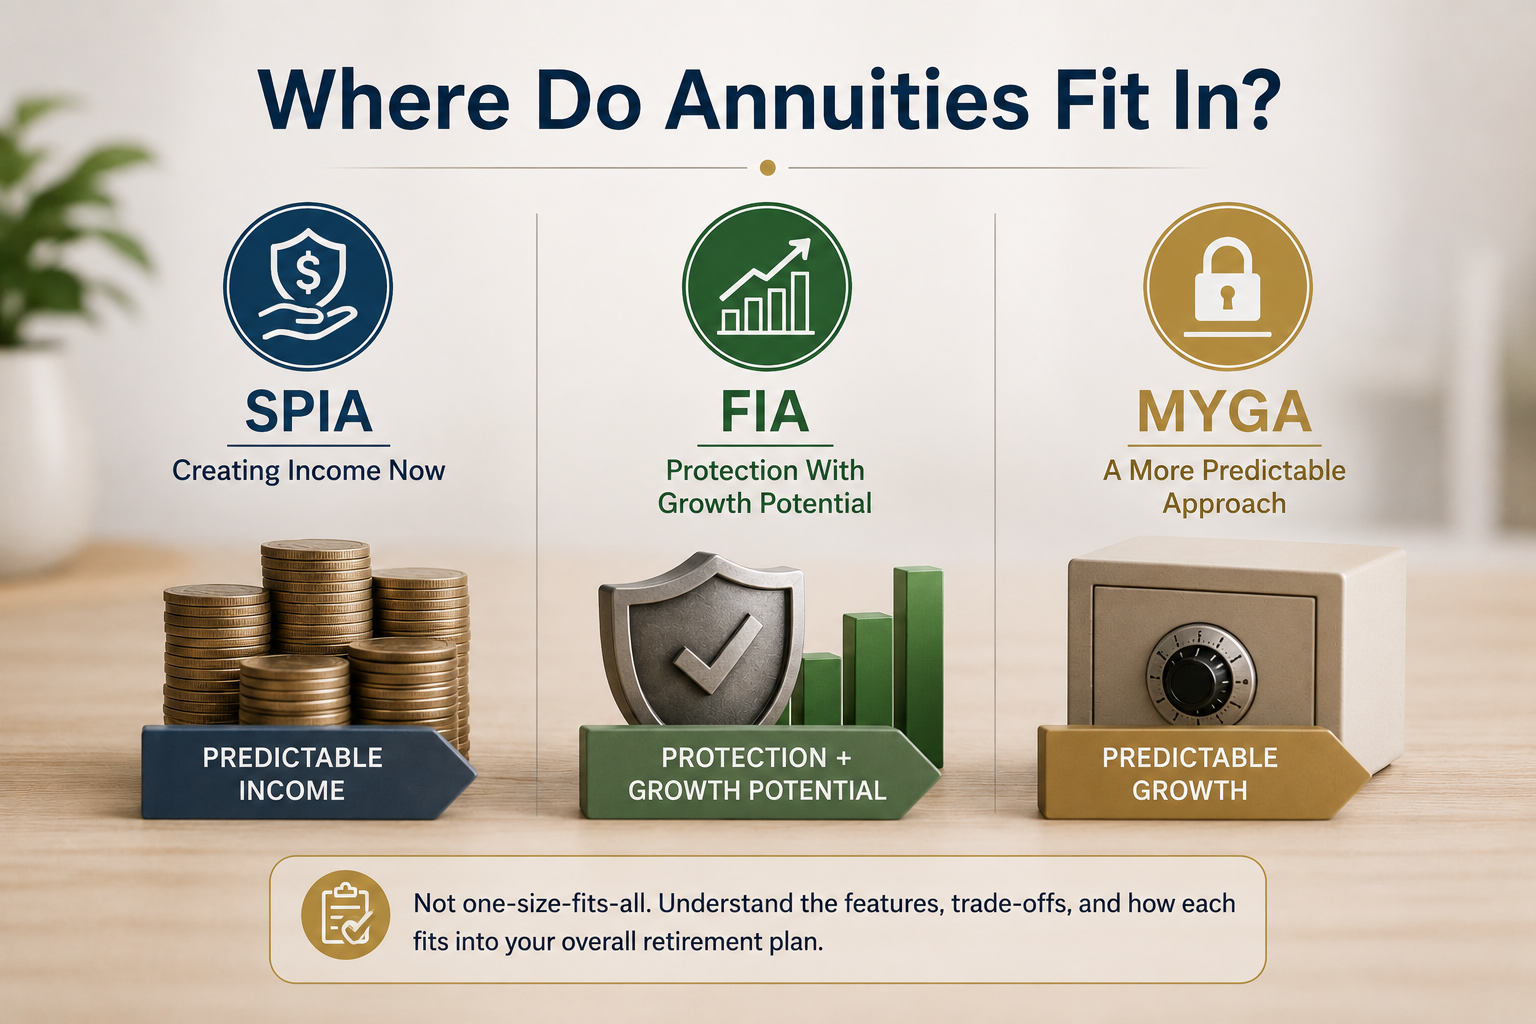
Where Do Annuities Fit In?
An annuity is a contract with an insurance company that can be used as part of a retirement strategy. Depending on the type and contract terms, annuities may be designed to provide income, accumulation, principal protection features, or a combination of these goals.
They're not appropriate for everyone, and there are several different types.
Three you may hear about are SPIAs, FIAs, and MYGAs.
SPIA: Creating Income Now
A Single Premium Immediate Annuity, or SPIA, is designed primarily for income.
You generally make a lump-sum premium payment to an insurance company, and in return, the insurer begins making payments based on the payout option selected.
For someone approaching or already in retirement who wants to convert a portion of savings into a predictable stream of income, a SPIA may be worth exploring.
The trade-off is important to understand: depending on the option selected, access to the original premium can be limited once income begins.
That's why the decision should be made as part of your overall financial picture rather than in isolation.
Fixed Indexed Annuities: Protection With Growth Potential
A Fixed Indexed Annuity, or FIA, works differently.
Interest credited to the contract can be linked in part to the performance of an external market index, subject to the contract's specific crediting method, caps, participation rates, spreads, and other terms.
Your money isn't directly invested in that index.
FIAs are designed to protect contract value from direct market losses while offering the potential for interest credits when the applicable index performs positively. Some contracts also offer optional income features.
There are trade-offs, including surrender periods, limits on access to funds, and contract-specific rules.
For the right person, an FIA may be one piece of a broader retirement strategy—but understanding exactly how the contract works is essential.
MYGAs: A More Predictable Approach
A Multi-Year Guaranteed Annuity, or MYGA, generally provides a guaranteed interest rate for a specified period, somewhat like the predictability people may associate with a certificate of deposit.
However, a MYGA is an insurance product, not a bank CD.
MYGAs may appeal to people who value predictable growth and don't want a portion of their retirement savings exposed to market volatility.
Again, liquidity provisions, surrender charges, taxes, insurer strength, and other contract terms should all be considered.
The Goal Isn't to Put Everything in One Place
This may be one of the most important parts of retirement planning.
Retirement doesn't necessarily require choosing between:
"Keep everything invested"
or
"Put everything into an annuity."
A thoughtful strategy may involve several different sources and types of assets serving different purposes.
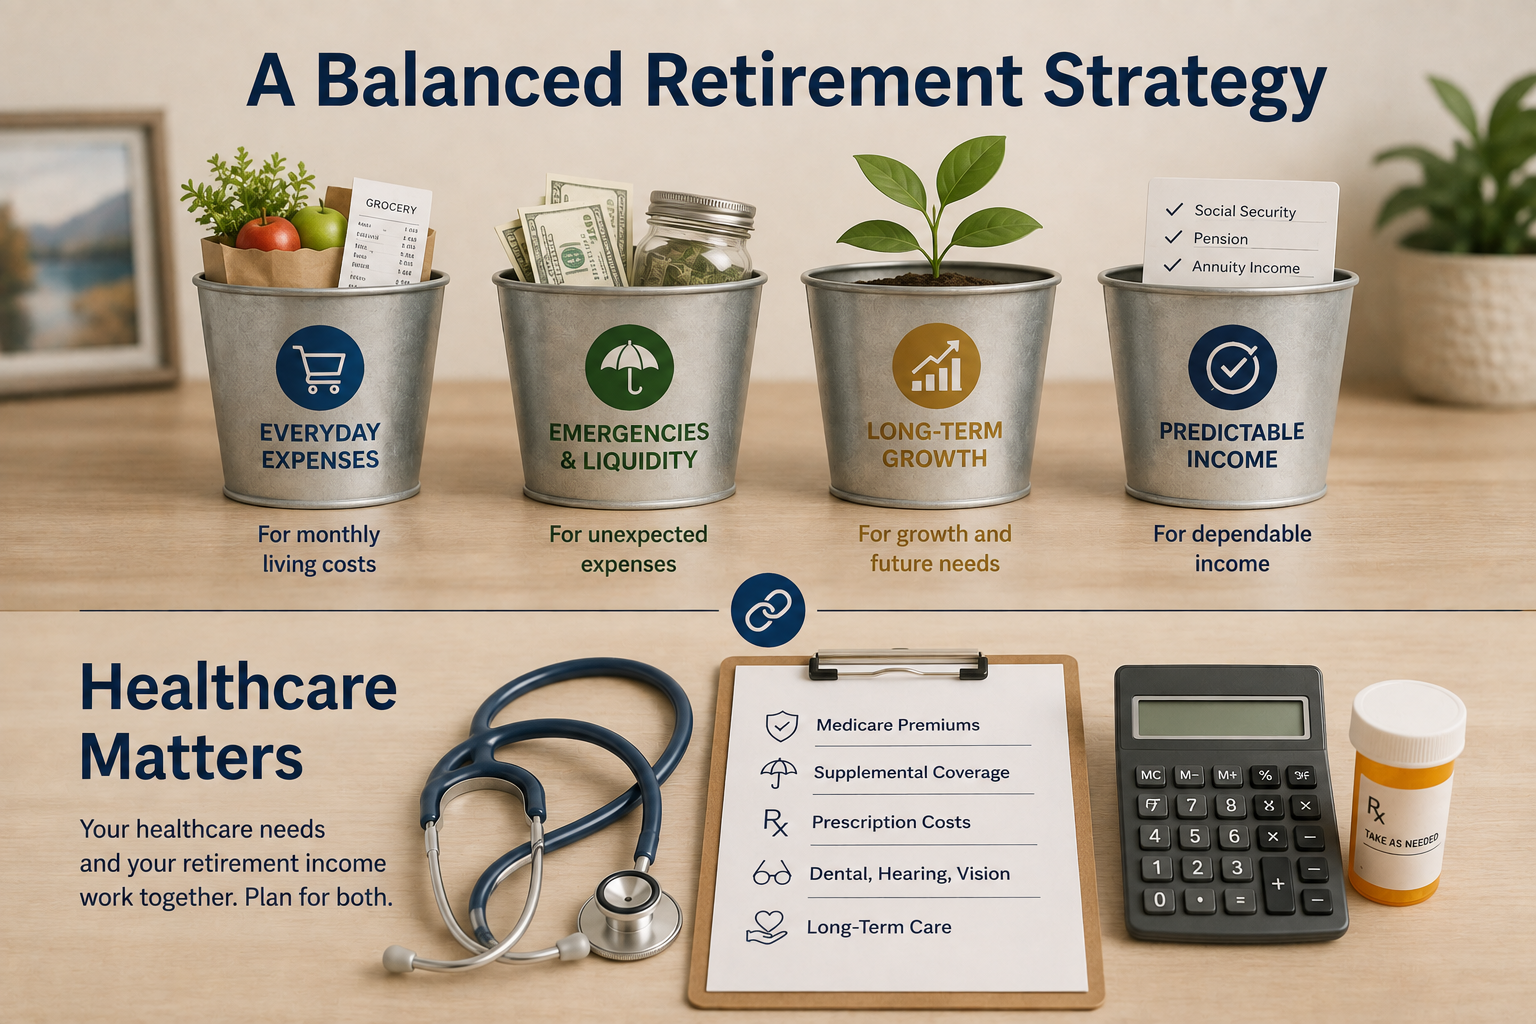
You might think about your retirement money in different "buckets":
One for everyday expenses.
One for emergencies and liquidity.
One for longer-term growth.
One for predictable income.
The exact strategy will depend on your financial situation, risk tolerance, income needs, and goals.
Don't Forget About Healthcare
Retirement income planning and healthcare planning belong in the same conversation.
As we age, healthcare may become a larger part of the household budget.
Medicare premiums, supplemental coverage, prescription costs, dental care, hearing, vision, and potentially long-term care needs can all affect retirement expenses.
At C & K, this is one reason we like looking at the whole person rather than one product.
Your Medicare decisions affect your retirement budget.
Your retirement income affects your ability to handle healthcare expenses.
Everything is connected.
Retirement Income Should Help You Live, Not Just Survive
There's another side of retirement planning that spreadsheets don't always capture.
What do you actually want to do?
Maybe you've spent 40 years dreaming about traveling.
Maybe you want to spoil the grandchildren a little.
Maybe you'd like to finally buy that camper.
Maybe your perfect retirement is simply sitting on the porch with coffee and knowing you don't have anywhere you're required to be.
Those goals deserve a place in the conversation too.
A Personal Thought
If I were entering retirement, I wouldn't want to spend every day staring at an account balance wondering whether I could afford to enjoy the money I'd spent decades saving.
I'd want to travel.
I'd want experiences with the people I love.
I'd want to say yes to dinner, vacations, family trips, and spontaneous adventures without feeling guilty every time I spent money.
Most of all, I'd want the confidence of knowing there was a thoughtful plan behind those decisions.
Because after spending your entire working life preparing for retirement, you should actually get to enjoy being retired.
At C & K Healthcare Advisors, Retirement Planning Starts With Listening
At C & K Healthcare Advisors, we're not interested in recommending an annuity simply because someone is retired.
First, we want to understand you.
What income do you already have?
What are your monthly expenses?
How important is access to your money?
How comfortable are you with market risk?
What do you want retirement to look like?
What are you hoping to leave to your family?
Only then does it make sense to discuss whether strategies involving SPIAs, fixed indexed annuities, MYGAs, or other options deserve consideration.
Annuity guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company, and annuity contracts can include surrender charges, tax considerations, and restrictions. Understanding those details matters.
The goal isn't to sell you an annuity. The goal is to help you create a retirement strategy that makes sense for your life.
You've Saved for Retirement.
Now Let's Help You Enjoy It.
Retirement represents decades of hard work.
Your financial strategy should help support the life you've been working toward.
If you're approaching retirement or already retired and wondering how to turn your savings into dependable income, C & K Healthcare Advisors is here to have that conversation with you.
We'll listen to your goals, help you understand your options, and explore strategies designed around your needs...not someone else's.
Contact C & K Healthcare Advisors for a personalized retirement income review. Because retirement isn't the finish line. It's the beginning of a chapter you've spent your whole career earning.
