Protecting Your Health Beyond Major Medical Insurance: Understanding Supplemental Coverage
Protecting Your Health Beyond Major Medical Insurance: Understanding Supplemental Coverage
Most of us understand why health insurance is important.
What can be easier to overlook is everything that can happen around a serious illness or hospital stay.
Imagine you're unexpectedly admitted to the hospital.
Your health insurance helps cover eligible medical care according to the terms of your plan.....but life outside the hospital doesn't suddenly stop.
The mortgage or rent is still due.
The electric bill still arrives.
Your spouse may be driving back and forth to the hospital.
There may be meals away from home, transportation expenses, household help, or other costs you never planned for.
And if you're still working, you may be worried about time away from your job.
That's where supplemental health coverage can become part of the conversation.
At C & K Healthcare Advisors, we believe protecting your health isn't only about having coverage for doctors and hospitals.
It's also about considering how an unexpected health event could affect the rest of your life.....and your family's finances.
What Is Supplemental Health Insurance?
Supplemental insurance is designed to supplement (not replace) your primary health insurance.
Depending on the type of policy, it may provide benefits when certain covered illnesses, injuries, hospitalizations, or other qualifying events occur.
Unlike traditional major medical insurance, some supplemental policies pay benefits directly to the policyholder based on the policy's terms.
That money may then provide additional financial flexibility while you're dealing with a covered health event.
The important distinction is this: Your health insurance primarily helps address eligible healthcare expenses. Supplemental coverage may help provide another layer of financial protection when life doesn't go according to plan.
Hospital Indemnity Insurance: When a Hospital Stay Affects More Than Your Health
Even with health insurance or Medicare coverage, a hospital stay can involve out-of-pocket costs.
Hospital indemnity insurance is designed to pay specified benefits when certain covered hospital services or stays occur, according to the policy.
Depending on the coverage, benefits might be based on events such as a hospital admission or the number of covered days spent in the hospital.
Those benefits can provide additional resources during recovery.
For someone living on a retirement budget (or a family trying to manage everyday expenses) having an additional source of funds after an unexpected hospitalization may be valuable.
Of course, hospital indemnity policies vary. Benefits, exclusions, limitations, waiting periods, and eligibility requirements should always be reviewed carefully.
Cancer, Heart Attack and Stroke Coverage
Few sentences can change a family's world faster than:
"You have cancer."
Or:
"You've had a heart attack."
Or:
"You've had a stroke."
In those moments, your first concern should be your health and the people you love.
Not wondering how every unexpected expense will be paid.
Cancer, heart attack and stroke coverage (sometimes grouped under critical illness-style protection) may provide a specified benefit after a covered diagnosis or event, depending on the policy.
That additional money may help provide financial flexibility for expenses associated with the disruption a serious illness can cause.
Every policy is different, so it's important to understand exactly which conditions are covered, how benefits are triggered, and what limitations or exclusions apply.
Health Insurance Can Cover the Treatment....but What About Everything Else?
Here's something many people don't think about until a serious diagnosis happens.
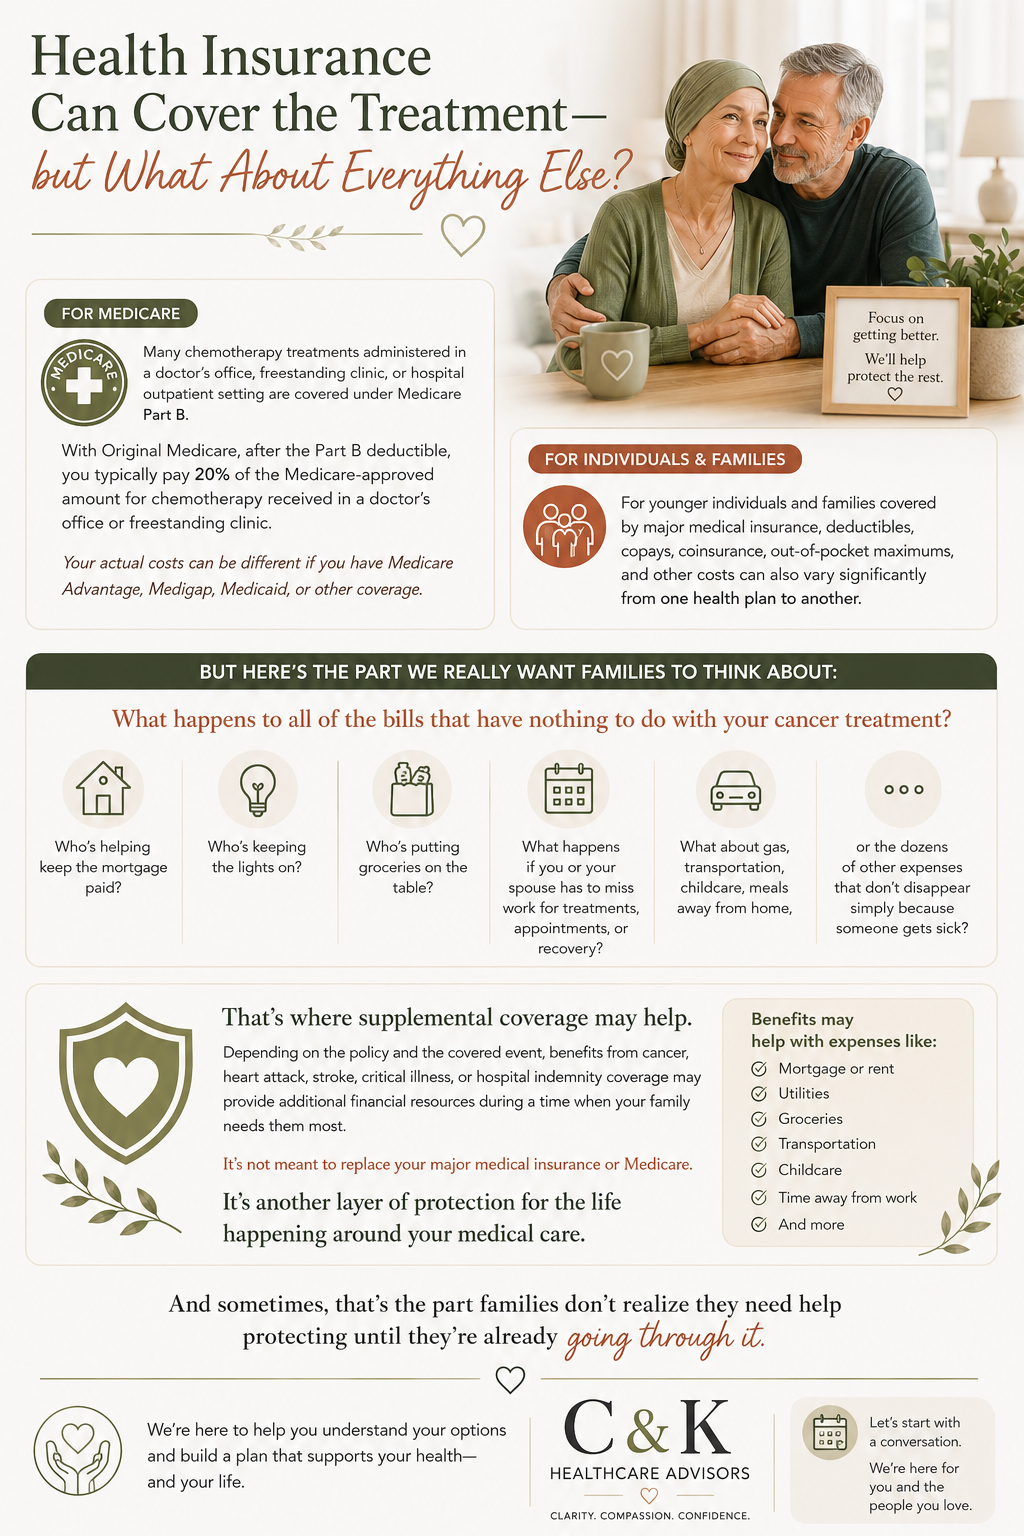
For someone on Medicare, many chemotherapy treatments administered in a doctor's office, freestanding clinic, or hospital outpatient setting are covered under Medicare Part B. With Original Medicare, after the Part B deductible, you typically pay 20% of the Medicare-approved amount for chemotherapy received in a doctor's office or freestanding clinic.
Your actual out-of-pocket costs can be very different depending on whether you have Original Medicare, Medicare Advantage, Medigap, Medicaid, or other coverage. And because cancer treatment can involve expensive medications, repeated treatments, testing, specialist visits, hospital care, and other services, the financial impact can become significant.
For seniors, this can often $10,000 or more.
For younger individuals and families covered by major medical insurance, costs can also add up quickly depending on the plan's deductible, copays, coinsurance, out-of-pocket maximum, provider network, and prescription coverage.
For younger individuals this number can be increasingly larger.
But here's the part we really want families to think about:
What happens to all of the bills that have nothing to do with your cancer treatment?
Your health insurance may help pay for covered medical treatment.
But who's helping keep the mortgage paid?
Who's keeping the lights on?
Who's putting groceries on the table?
What happens if you or your spouse has to miss work for treatments, appointments, or recovery?
What about gas, transportation, childcare, meals away from home, or the dozens of other expenses that don't disappear simply because someone gets sick?
The medical bills are only one part of the financial impact a serious illness can have on a family.
That's where supplemental coverage may help.
Depending on the policy and the covered event, benefits from cancer, heart attack, stroke, critical illness, or hospital indemnity coverage may provide additional benefits that give you greater financial flexibility during an already difficult time.
It's not meant to replace your major medical insurance or Medicare.
It's another layer of protection for the life happening around your medical care.
Because if you or someone you love is facing a serious diagnosis, your family's energy should be focused on treatment, recovery, and being together.
Not wondering how you're going to keep the lights on.
Why This Can Matter in Retirement
Retirement can make these conversations especially important.
While you're working, you may have a paycheck arriving every week or two.
Once retired, you may be living on a combination of Social Security, pension income, retirement savings, investments, or annuity income.
An unexpected expense can have a different impact when you're trying to preserve those resources for the rest of your retirement.
That's why healthcare and retirement planning shouldn't always be treated as two completely separate conversations.
Your health can affect your finances.
And your financial preparedness can affect how confidently you're able to navigate an unexpected health event.
Supplemental Coverage Isn't About Having Every Policy Available
This is important.
More insurance isn't automatically better.
You don't necessarily need every supplemental product that exists.
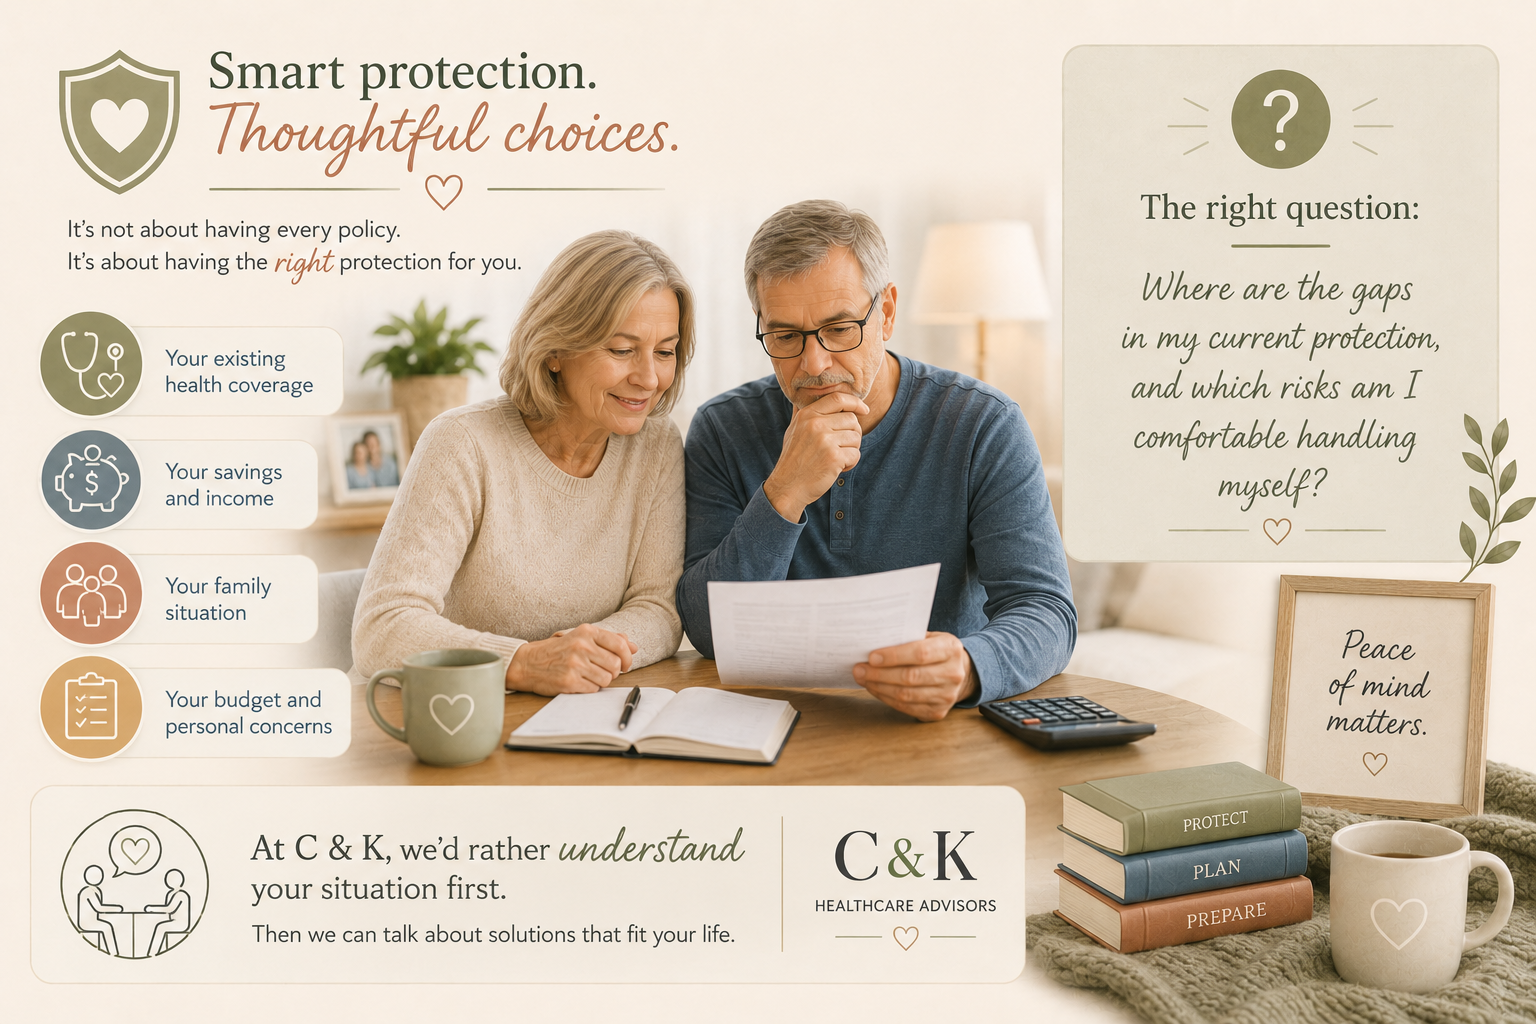
The right question is:
"Where are the gaps in my current protection, and which risks am I comfortable handling myself?"
For example, one person may already have enough savings to comfortably handle unexpected out-of-pocket expenses.
Someone else may prefer the predictability of transferring some of that financial risk to an insurance policy.
Your existing health coverage, savings, income, family situation, budget, and personal concerns should all be part of the decision.
At C & K, we'd rather understand those things first than start by showing you a product.
What Should You Ask Before Choosing Supplemental Coverage?
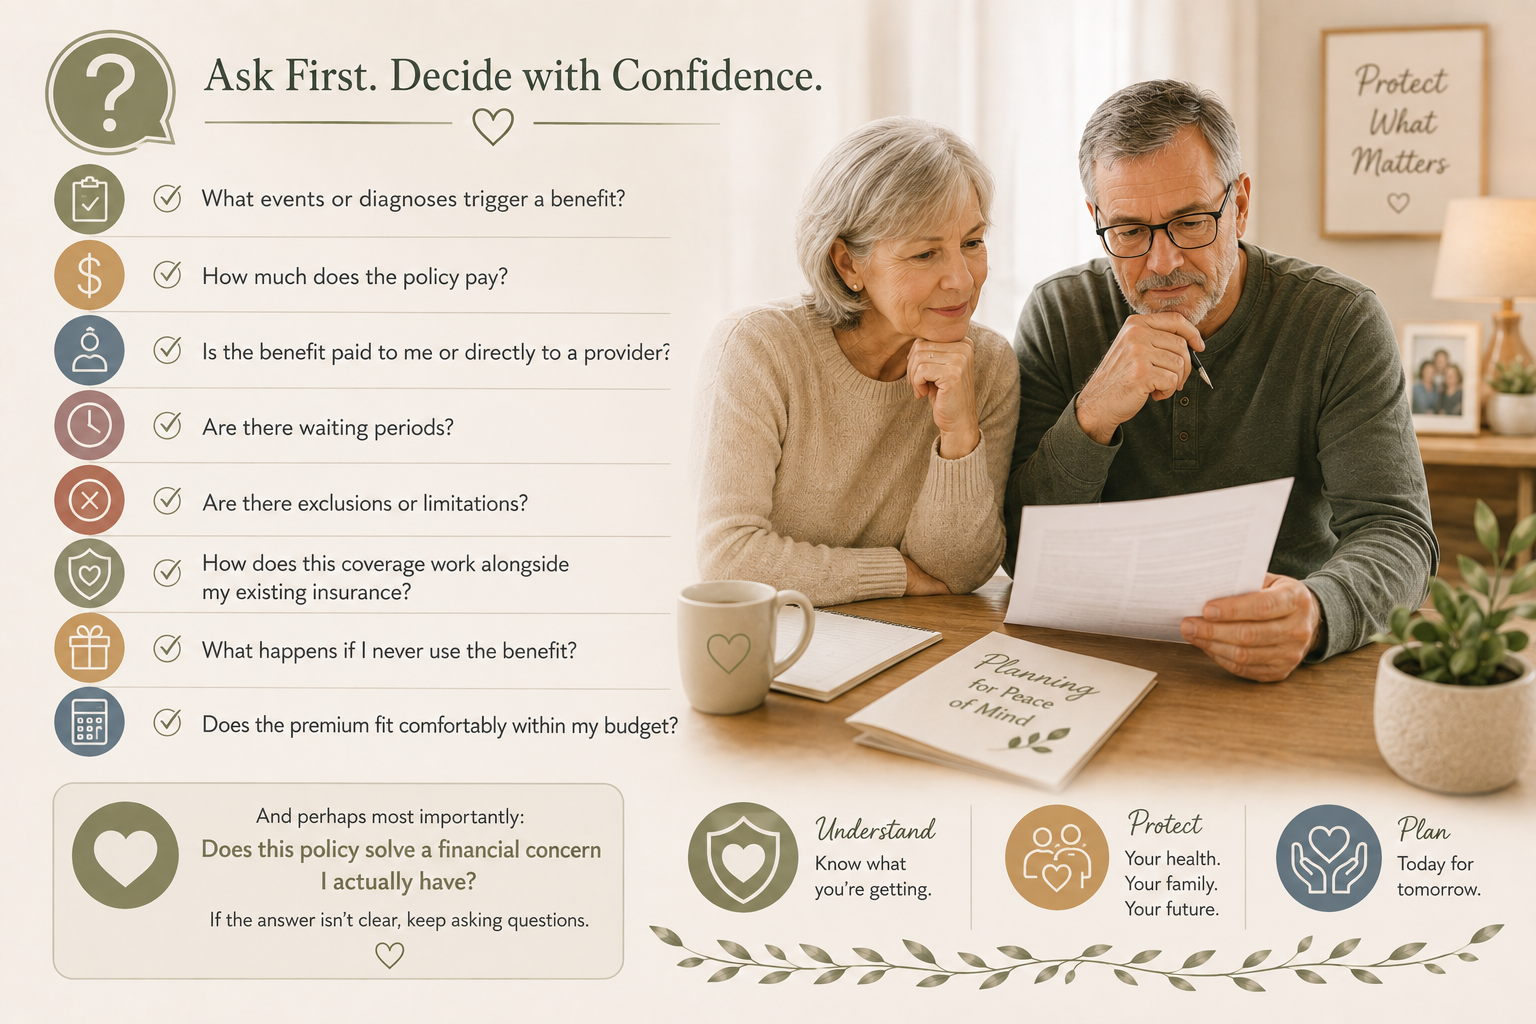
Before enrolling in any supplemental health policy, make sure you understand what you're purchasing.
Ask questions such as:
What events or diagnoses trigger a benefit?
How much does the policy pay?
Is the benefit paid to me or directly to a provider?
Are there waiting periods?
Are there exclusions or limitations?
How does this coverage work alongside my existing insurance?
What happens if I never use the benefit?
Does the premium fit comfortably within my budget?
And perhaps most importantly:
Does this policy solve a financial concern I actually have?
If the answer isn't clear, keep asking questions.
A Personal Thought
If someone I loved were facing cancer, a heart attack, a stroke, or an unexpected hospitalization, I know exactly what I'd want them thinking about:
Getting better.
I'd want our family focused on appointments, recovery, sitting together, bringing meals, telling stories, making them laugh, and simply being there.
I wouldn't want the conversation at the kitchen table every night to be about bills.
We can't remove every worry that comes with a serious health event. But I love the idea of planning ahead so that, if one of those difficult moments ever arrives, a family has one less thing competing for their attention.
To me, that's what protection should really be about.
At C & K Healthcare Advisors, We Look at the Whole Picture
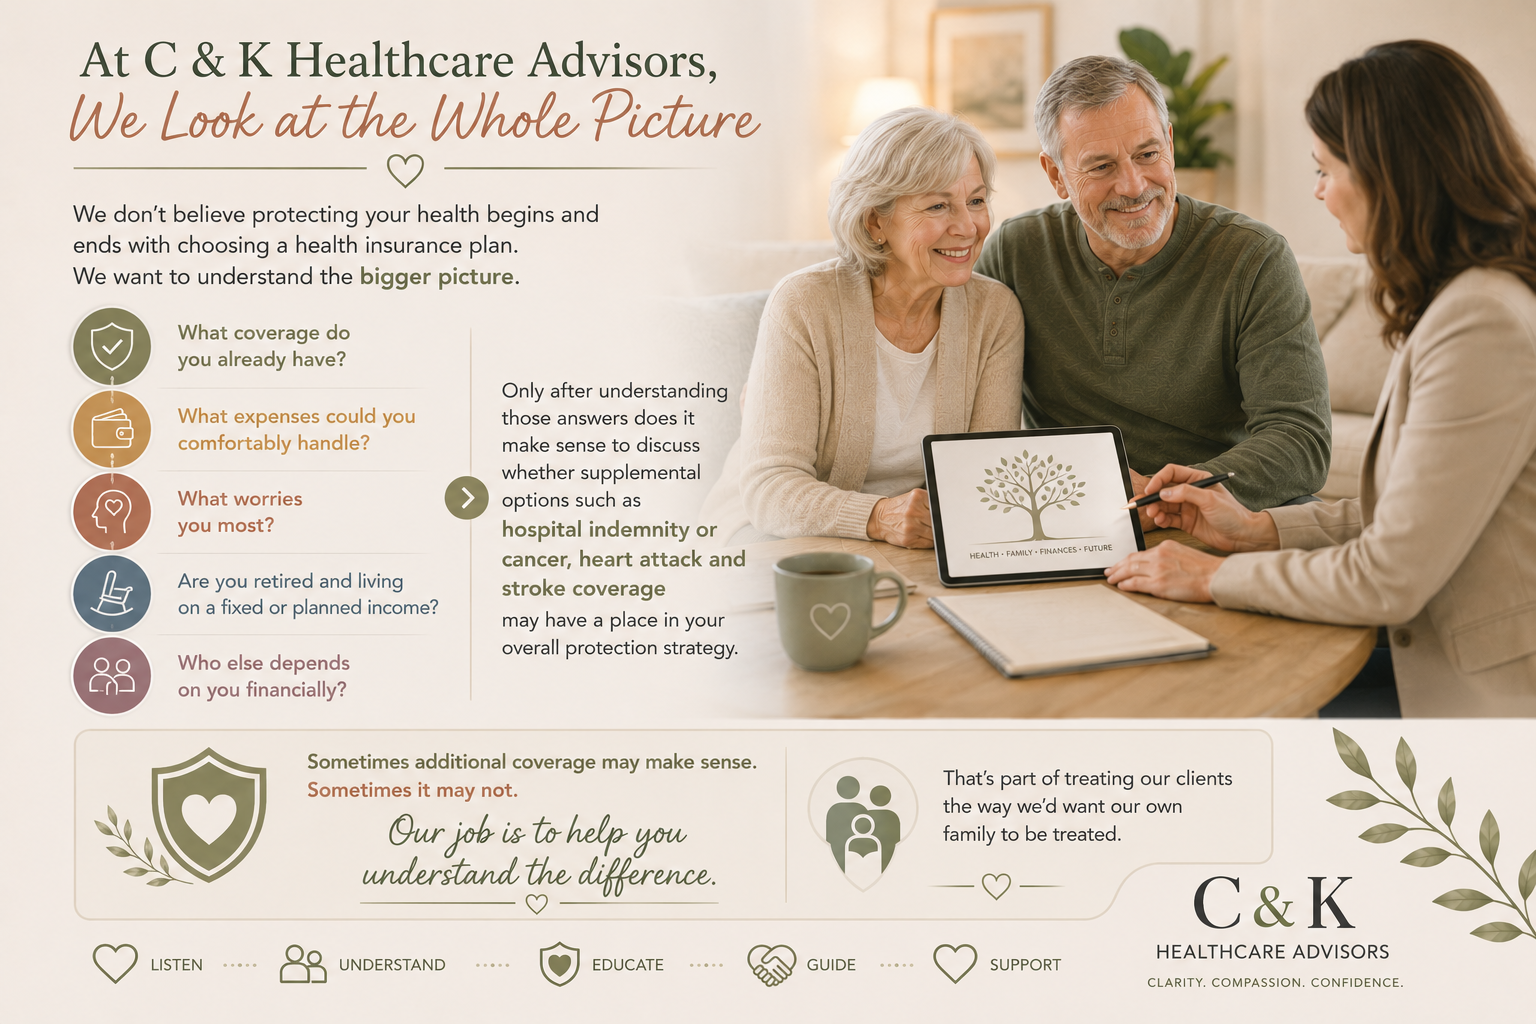
At C & K Healthcare Advisors, we don't believe protecting your health begins and ends with choosing a health insurance plan.
We want to understand the bigger picture.
What coverage do you already have?
What expenses could you comfortably handle?
What worries you most?
Are you retired and living on a fixed or planned income?
Who else depends on you financially?
Only after understanding those answers does it make sense to discuss whether supplemental options such as hospital indemnity or cancer, heart attack and stroke coverage may have a place in your overall protection strategy.
Sometimes additional coverage may make sense.
Sometimes it may not.
Our job is to help you understand the difference.
That's part of treating our clients the way we'd want our own family to be treated.
Protect Your Health, and the Life Around It
Health insurance is incredibly important.
But your life is bigger than a medical bill.
It's your home, your retirement, your family, your everyday expenses, and the people you'd want beside you if something unexpected happened.
If you're wondering whether there are gaps in your current healthcare protection, C & K Healthcare Advisors would be happy to help you take a closer look.
We'll listen to your concerns, review your existing protection, explain your options in everyday language, and help you decide what makes sense for you.
Contact C & K Healthcare Advisors for a personalized coverage review.
Because when life changes unexpectedly, having a thoughtful plan in place can help you focus more of your energy where it belongs.
On your health and the people you love.